Whatshot

2026
All
September
2025
All
November
All
2024
All
June
All
April
All
2023
All
March
All
2022
All
2021
All
2020
All
March
All
February
All
2019
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
May
All
April
All
March
All
February
All
2018
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
May
All
April
All
March
All
February
All
2017
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
May
All
April
All
March
All
February
All
January
All
2016
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
May
All
April
All
March
All
February
All
January
All
2015
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
May
All
DHS
April
All
March
All
February
All
January
All
2014
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
KZN
May
All
April
All
March
All
February
All
January
All
2013
All
December
All
November
All
October
All
September
All
August
All
July
All
June
All
May
All
April
All
March
All
February
All
January
All
2012
All
December
All
November
All
October
All
September
All
August
All
July
All

Bugle Sales Talk Editorial

Bugle Sales Talk Editorial

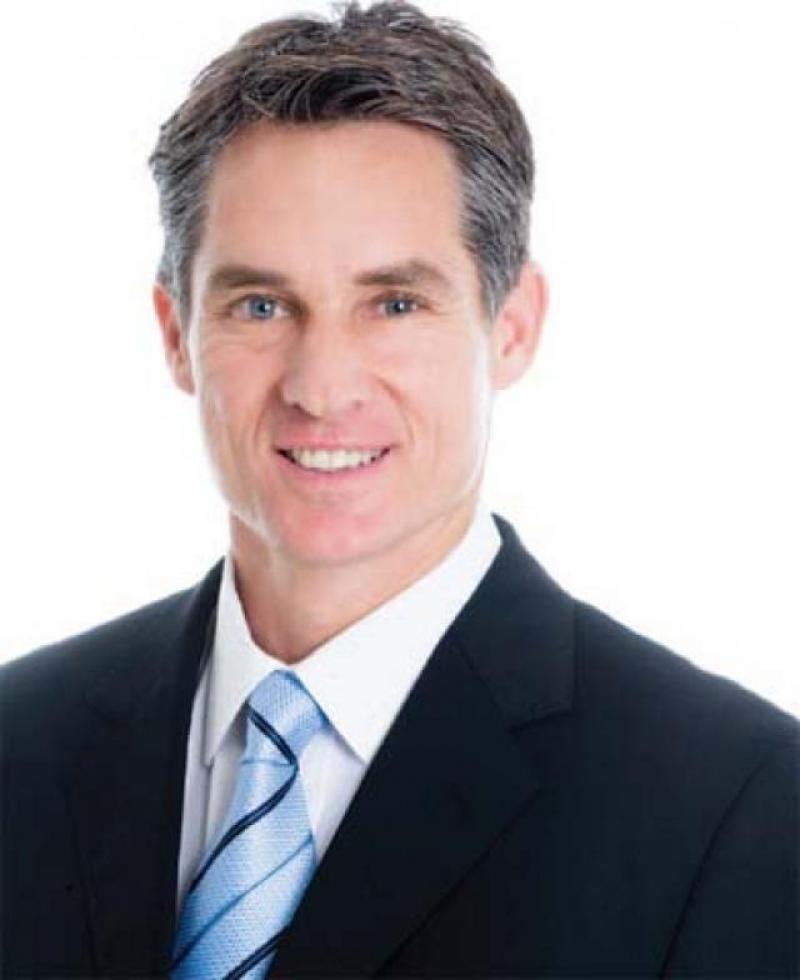
Author: Andreas Wassenaar
Date: 2016-03-25
The important property headline news items that you should be aware of is that the Reserve Bank increased its policy repo rate by 25 basis points to 7% on the 18th March, which resulted in commercial banks in South Africa immediately increasing their prime interest rate to 10,5%. Headline CPI inflation is currently at 6,2%, just above the upper limit of the 6% target range the Reserve Bank has set for itself. The producer price index (PPI) measure of inflation relates to the inflation rate of manufactured goods which is currently at 7,6% and will therefore continue to provide upward pressure on the CPI. It is widely expected that further gradual interest rate hiking will occur and that the prime rate will peak at 11% in the first half of next year. Two drivers of local CPI inflation remain the deteriorating Rand exchange rate and the spike in food prices. Given the recent rain experienced along the Dolphin Coast you would not think a severe drought is impacting on food prices but the extreme 25,9% inflation in the producer price index for Agriculture is sobering as it points to a significant rise in the CPI inflation rate for food in the coming months. According to FNB the higher interest rates, lower levels of economic growth and lower levels disposable income are expected to reduce the number and value of new mortgage bonds registered as well as lead to a rise in existing mortgage loans in arrears. These arrears are projected to increase from the current level of 3,5% of the value of total household sector mortgage loans outstanding to 3,7% for 2016, 4,2% in 2017 and as high as 4,8% for 2018. This level is however not as severe as the 9,2% reached in 2010. Economic growth is projected to dip further in 2016 to 0,5%, which would make this year the 5th consecutive year of growth slowdown. Average house price growth is forecast to slow from 6% last year, to 4,8% in 2016 and further to 3,1% in 2017. The forecast for the Rand: US Dollar exchange rate published by FNB puts the average rate at 16.58 for 2016; 16.31 for 2017 and 16.80 for 2018. Clearly the expectation is that the value of the Rand will stabilize at the current level of around R16 to the US Dollar rather than continue to weaken much further. This will be important for buyers who are currently importing funds to purchase a South African residential property as they will typically want to have some idea of what the exchange rate risk will be over the next few years.

When the macro-economic environment starts to provide signs of tougher times ahead, as it is currently doing, the smart money starts to focus on the obvious buying opportunities that may result. If we accept that new mortgage loan growth is going to be lower over the next year or two and interest rates remain at higher levels, then the opportunistic strategy is to prepare to buy high yielding rental properties where the current owners may be leveraged beyond their sustainable levels. For me the sweet spot is an initial gross yield of 9% on capital. If I can achieve this by buying a well-located property, where the upside potential is relatively high, then I am satisfied. Given the influx of families into our area, the demand for rental properties far outstrips the supply and this is unlikely to change any time soon.

You will need to have a personal balance sheet strong enough to satisfy the banks that you can service a given level of debt, but assuming that you can, then the next two to three years may provide the investment opportunities you have been waiting for.

For further information and an interactive analysis of this article follow my blog: andreaswassenaar.blogspot.com.

Andreas Wassenaar

Principal - Seeff Dolphin Coast

Cell: 082 837 9094

andreasw@seeff.com